Average and Median Net Worth by Age in the U.S. (and How to Compare Yours)
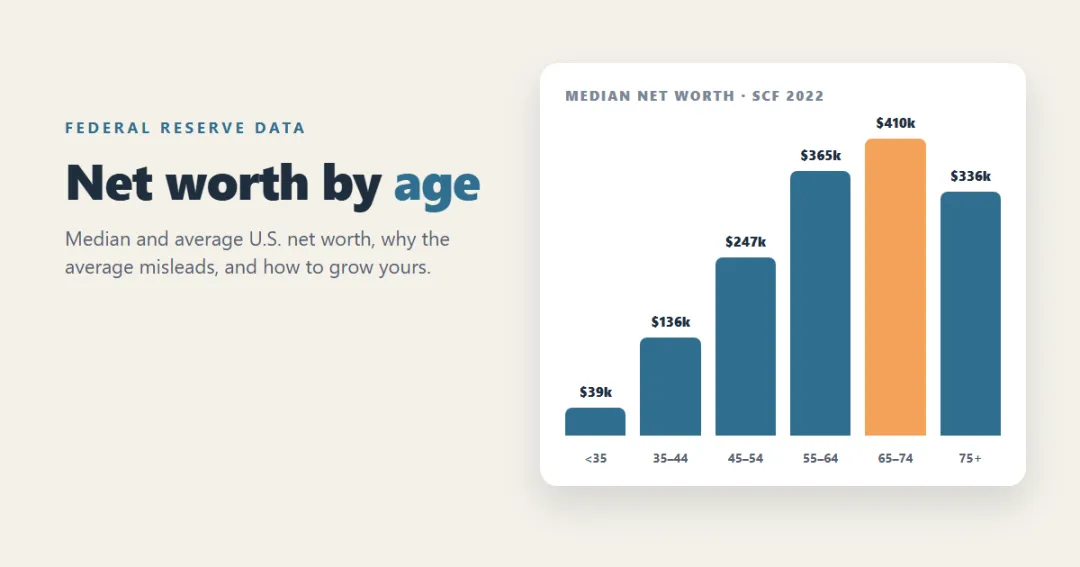
The typical American household under 35 has a net worth of about $39,000; at 65–74 it's about $410,000. Here's the latest Federal Reserve data on median and average net worth by age, why the average is so misleading, useful savings benchmarks by age, and how to grow your own number at any stage.
In this article
"Am I on track?" is one of the most common money questions, and net worth by age is the most common way people try to answer it. The numbers are interesting, but they're easy to misread. This guide gives you the latest official data, explains why the "average" figures you see in headlines are misleading, offers more useful benchmarks, and shows how to grow your own number at any age.
To work out your own net worth in a few minutes, use the free net worth calculator.
Net worth by age: the data
The best source is the Federal Reserve's Survey of Consumer Finances (SCF), run every three years. The latest published survey covers 2022; the next, covering 2025, is expected in late 2026.
| Age of household head | Median net worth | Average (mean) net worth |
|---|---|---|
| Under 35 | $39,000 | $183,500 |
| 35–44 | $135,600 | $549,600 |
| 45–54 | $247,200 | $975,800 |
| 55–64 | $364,500 | $1,566,900 |
| 65–74 | $409,900 | $1,794,600 |
| 75 and older | $335,600 | $1,624,100 |
Figures in 2022 dollars, Federal Reserve SCF 2022. Net worth includes home equity, retirement accounts, businesses and other assets, minus all debts.
Median vs average: why the difference matters
The average in every age group is four to five times the median. That's because a relatively small number of very wealthy households pull the average up. If ten people have $100,000 each and one has $10 million, the average is about $1 million, but nobody typical has anything close to that.
Use the median to compare yourself with a typical household. Use your own past numbers to see whether you're improving, which matters most.
Why net worth rises with age, then dips
- Under 35: student loans, first car loans and small savings; many households start near zero or below.
- 35–54: income rises, mortgages get paid down, retirement accounts compound.
- 55–74: peak net worth, close to or just after retirement.
- 75+: retirees spend down savings, so the median falls.
More useful benchmarks
Comparing with national figures says little about your situation; your income, location and goals matter more. Many planners use salary-based savings milestones for retirement accounts instead:
| Age | Retirement savings milestone |
|---|---|
| 30 | about 1× your salary |
| 40 | about 3× |
| 50 | about 6× |
| 60 | about 8× |
| 67 | about 10× |
These are rough guides for a traditional retirement, not rules. If you want to retire early, the target is based on spending instead: about 25 times your yearly spending, explained in our guide to the FIRE movement.
What if you're behind?
Most people feel behind; the data shows that the typical household is far below the averages in the headlines. What matters is direction:
- Negative net worth in your 20s is common with student loans. Paying them down raises your net worth every month; our guide to paying off student loans faster shows how.
- Catch-up contributions let people 50 and older put extra into 401(k)s and IRAs; see the 401(k) calculator.
- Time still matters at any age: the compound interest calculator shows how much a decade of steady investing adds.
How to grow your net worth at any age
- Spend less than you earn and automate saving on payday.
- Pay off high-interest debt first; it's a guaranteed return. See the debt payoff calculator.
- Get the full employer 401(k) match, then fund a Roth IRA.
- Invest for the long term in diversified, low-cost funds.
- Avoid new debt on things that lose value, especially expensive cars; the how much car can I afford calculator helps keep it sensible.
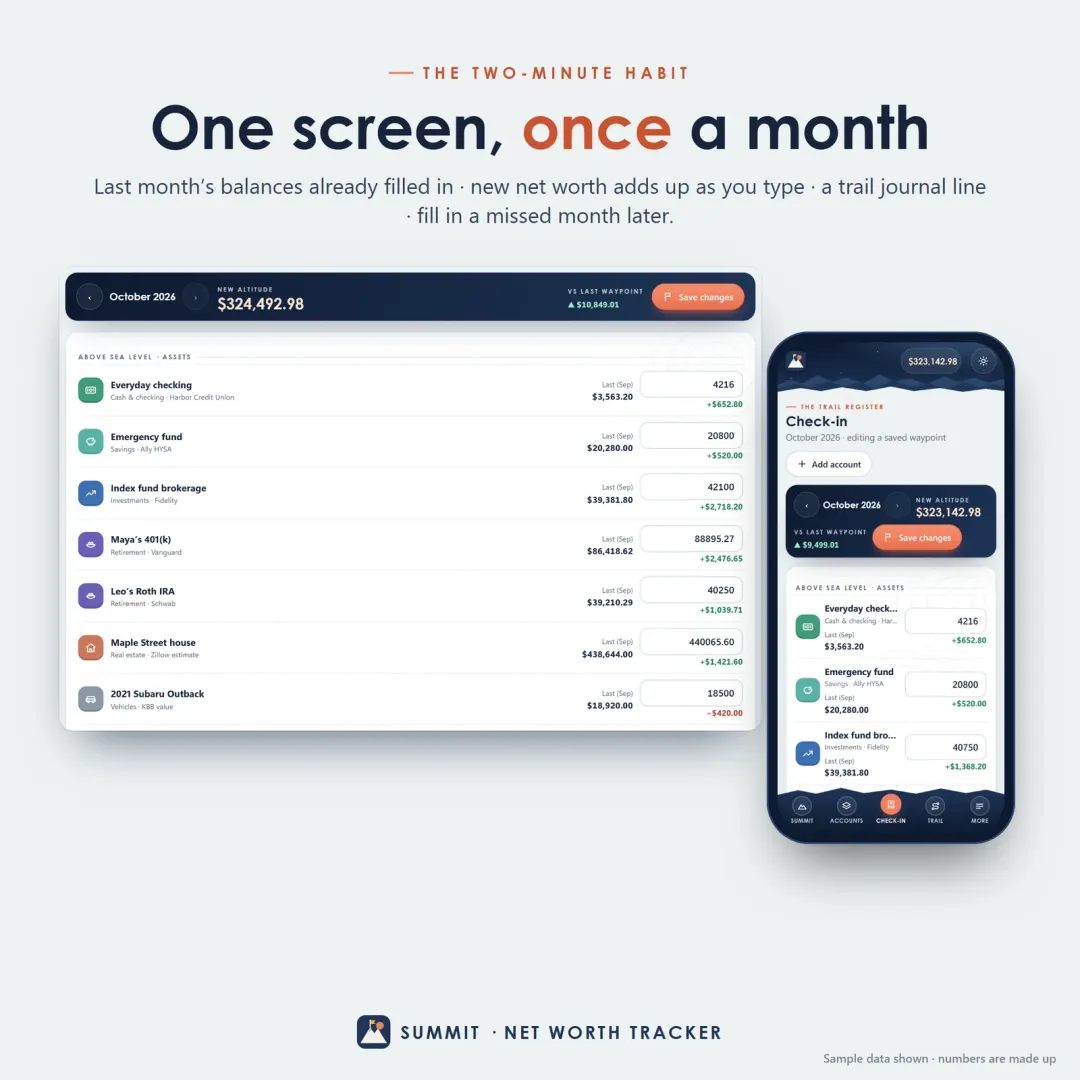
- Track it monthly. What gets measured gets improved.
How to calculate your own net worth
Net worth = everything you own − everything you owe.
- Assets: cash, savings, investments, retirement accounts, home value, car value, other valuables.
- Liabilities: mortgage, car loans, student loans, credit cards, personal loans.
Our step-by-step guide on how to calculate your net worth walks through valuing a home and car honestly, liquid net worth and debt-to-asset ratio, or use the net worth calculator to do it in minutes.
Track your number, not the average
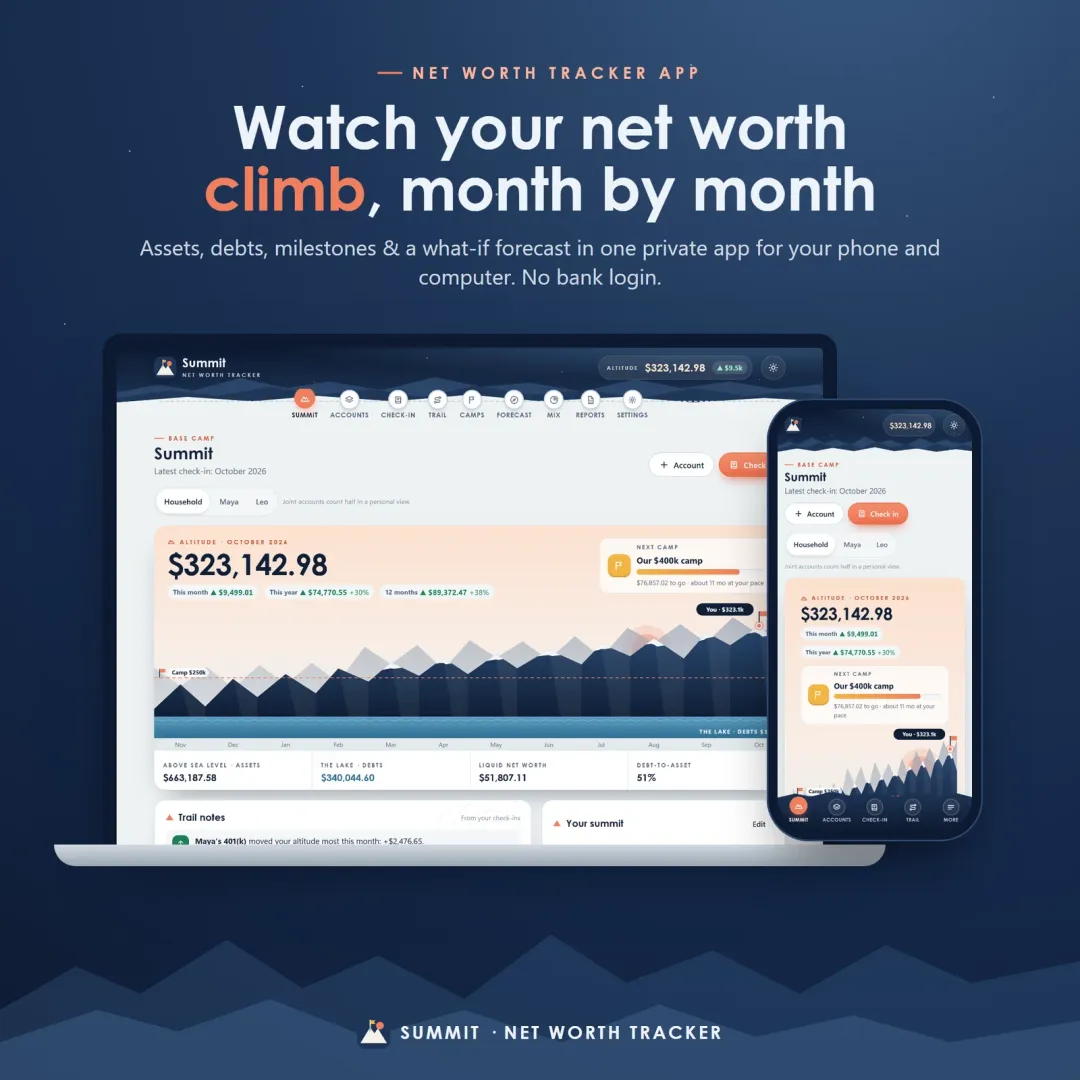
Summit is a net worth tracker built for exactly this: a monthly check-in with every account, a history chart over months and years, milestones and a forecast of where you're heading. Vault keeps your budget and goals in one dashboard, and Zero turns debts into a payoff plan that raises your net worth every month. Each has a free demo with sample data you can open in your browser.
The short version
- Typical (median) net worth: $39,000 under 35, $135,600 at 35–44, $247,200 at 45–54, $364,500 at 55–64, $409,900 at 65–74.
- Averages are far higher because of a few very wealthy households; compare with the median.
- Salary-based milestones (1× at 30, 3× at 40, 6× at 50) are more useful guides.
- Direction beats the number: track monthly and keep it rising.
- Find yours with the net worth calculator.
Data: Federal Reserve, Survey of Consumer Finances 2022. General education, not financial advice.
Frequently asked questions
What is the average net worth by age?
What is the median net worth by age?
Why is average net worth so much higher than median?
What is a good net worth at 30?
Does net worth include my home?
How often should I check my net worth?
Written by
Finance Specialist & Editor, VaultlyApps
Emma Whitfield writes and edits the VaultlyApps money guides and free calculators. Her focus is US household finance — budgeting on a real paycheck, paying down credit card and student debt, emergency funds and savings goals, renting — and the money side of freelancing and small-business income, from pricing and profit margins to self-employment tax. Every guide is researched against primary sources such as IRS publications and the CFPB, every number is checked in our tested calculators, and tax content is reviewed each year when new IRS figures come out. Emma is not a licensed financial adviser or tax preparer; her work is general education, not personal advice.
Researched against primary US sources, checked with our calculators and reviewed by a finance expert on our team. Written for US readers — general education, not financial, tax or legal advice. Editorial policy · Disclaimer