How to Calculate Your Net Worth (With a Real Example and a Monthly Tracking Plan)
Net worth is everything you own minus everything you owe. Here's how to list your assets and debts, value your home and car honestly, work out liquid net worth and debt-to-asset ratio, and track the number monthly so you can see real progress.
In this article
- The net worth formula
- Step 1: List everything you own (your assets)
- How to value the tricky ones
- Step 2: List everything you owe (your liabilities)
- Step 3: Subtract
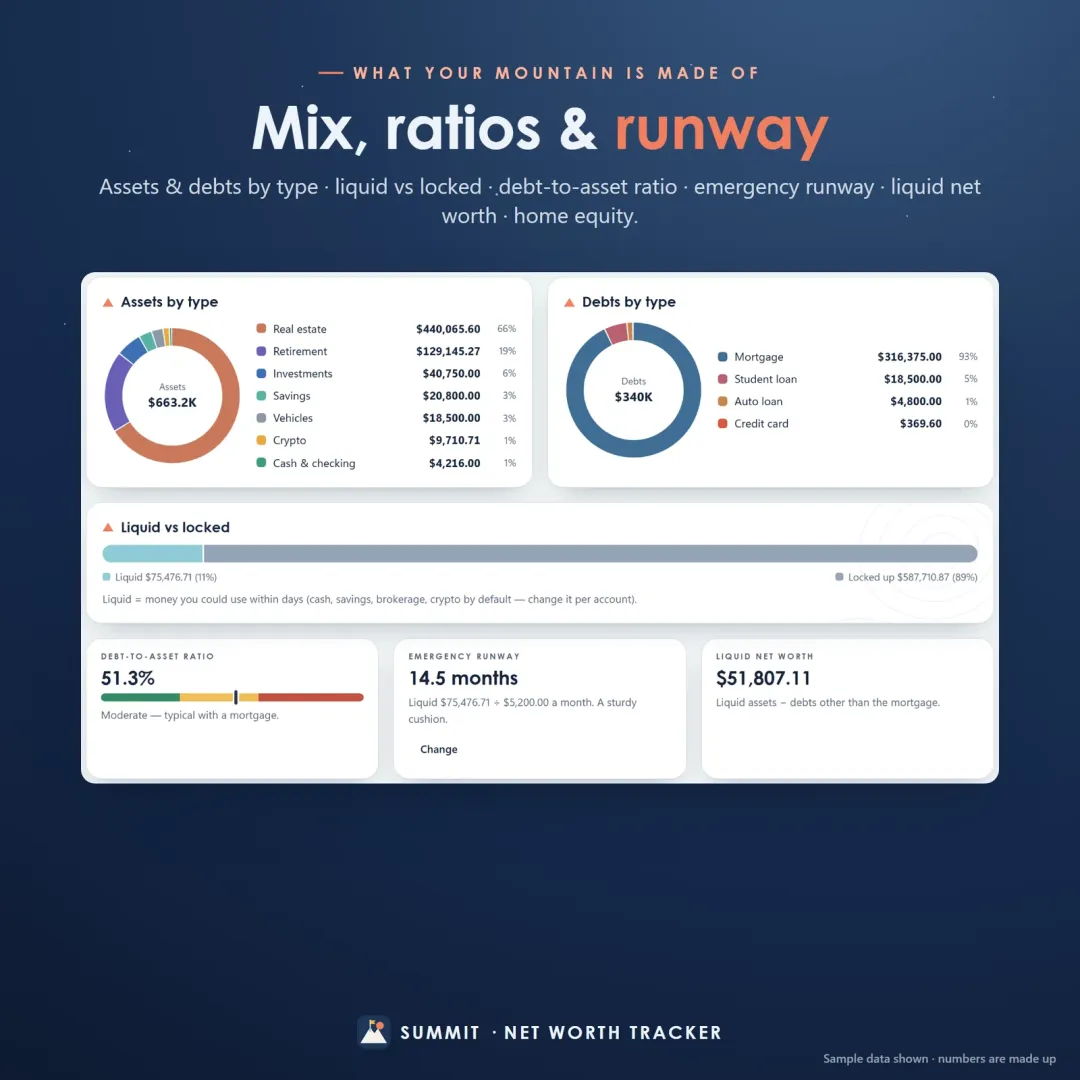
- Step 4: Work out your liquid net worth
- Step 5: Check your debt-to-asset ratio
- Why one number isn't enough: track it monthly
- A simple monthly net worth routine
- Track your net worth with Summit
- How to grow your net worth
- Common net worth mistakes
- The bottom line
Your net worth is the single number that sums up your whole financial life: everything you own minus everything you owe. It doesn't care how much you earn or how fancy your car is — only how much would be left if you sold what you own and paid off every debt. That's why it's the best measure of real progress, and why tracking it month after month is one of the most motivating money habits you can build.
This guide walks through how to calculate your net worth step by step, with a full worked example, how to value the tricky things (your home, car and retirement accounts), the two extra numbers worth knowing — liquid net worth and debt-to-asset ratio — and a simple plan to track it every month.
If you'd rather jump straight to the numbers, the free net worth calculator does all of this in a minute.
The net worth formula
Net worth = total assets − total liabilities
- Assets are things you own that have a cash value: money in the bank, investments, retirement accounts, your home, your car, valuables, a business.
- Liabilities are what you owe: credit card balances, student loans, car loans, a mortgage, personal and medical debt.
If your assets add up to more than your liabilities, your net worth is positive. If you owe more than you own, it's negative — which is common and nothing to be ashamed of, especially early on.
Step 1: List everything you own (your assets)
Grab your latest statements or log in to each account, and write down today's value of:
- Cash and checking — every checking account, plus cash you keep.
- Savings — high-yield savings, your emergency fund, money market accounts, CDs.
- Investments — brokerage accounts, index funds, individual stocks, bonds.
- Retirement accounts — 401(k), 403(b), IRA, Roth IRA, pension (the current value shown on your statement).
- Real estate — your home and any rental property, at realistic market value.
- Vehicles — cars, motorcycles, boats, at what they'd sell for today.
- Crypto — at today's price.
- Business — the value of a business you own, if you can estimate it fairly.
- Valuables and other — jewelry, collectibles or equipment you could actually sell. Most household items (furniture, clothes, electronics) are worth far less than you paid; many people leave them out.
How to value the tricky ones
- Your home: use a recent appraisal, the sold prices of similar homes nearby, or an online home-value estimate. Don't use what you paid or what you hope to get. Some people subtract around 6% for selling costs to be conservative.
- Your car: use a used-car guide's private-party or trade-in value, not the price you paid. Cars lose value every year, so update it every few months.
- Retirement accounts: use the balance on the statement. If you want to be cautious, you can reduce it by an estimated tax rate, since traditional 401(k) and IRA withdrawals are taxed. Whatever you choose, do it the same way every month.
- Things you can't sell easily: if you wouldn't realistically sell it, or it's worth little second-hand, leave it out. A net worth figure that flatters you is less useful than an honest one.
Step 2: List everything you owe (your liabilities)
Now list the current balance of every debt — not the monthly payment:
- Credit cards — the statement balance or today's balance.
- Student loans — federal and private.
- Auto loans.
- Mortgage — and any home equity loan or HELOC.
- Personal loans, buy-now-pay-later plans and loans from family.
- Medical debt and anything else you owe.
The payoff amount on a loan statement is usually the most accurate number.
Step 3: Subtract
Add up each list and subtract liabilities from assets. Here's a worked example for a household with a home, a car loan and some student debt:
| What you own | Value | What you owe | Balance |
|---|---|---|---|
| Home (market value) | $320,000 | Mortgage | $248,000 |
| Checking & savings | $14,500 | Car loan | $9,500 |
| Emergency fund | $9,000 | Student loan | $21,000 |
| 401(k) / IRA | $62,000 | Credit card | $2,400 |
| Brokerage account | $18,000 | ||
| Car (resale value) | $16,000 | ||
| Total assets | $439,500 | Total liabilities | $280,900 |
Net worth = $439,500 − $280,900 = $158,600.
That's the headline number. But two more figures tell you much more about how solid it is.
Step 4: Work out your liquid net worth
In the example, most of the net worth sits in home equity ($320,000 − $248,000 = $72,000) and a retirement account ($62,000). Neither is easy to spend if the car breaks down or a job ends.
Liquid net worth answers a more practical question: how much could you actually reach within days?
Liquid net worth = liquid assets − debts other than the mortgage
- Liquid assets: $14,500 + $9,000 + $18,000 = $41,500
- Non-mortgage debts: $9,500 + $21,000 + $2,400 = $32,900
- Liquid net worth = $8,600
So a household with a "$158,600 net worth" has an $8,600 real cushion. That's not a problem — but it shows exactly where to focus: build the emergency fund and pay off the card and car loan. Read what liquid net worth means and use the emergency fund calculator to pick a target.
Step 5: Check your debt-to-asset ratio
Debt-to-asset ratio = total liabilities ÷ total assets × 100
In the example: $280,900 ÷ $439,500 = 63.9%. In plain words, for every $100 this household owns, it owes about $64.
| Ratio | What it usually means |
|---|---|
| Under 30% | Low — most of what you own is yours. |
| 30% – 60% | Moderate — common with a mortgage. |
| Over 60% | High — debts are a big share of your assets. |
A high ratio with a young mortgage is normal; it falls every month as the loan is paid down and savings grow. If it's high because of credit cards or personal loans, that's the place to start. More in debt-to-asset ratio explained. Don't confuse it with the debt-to-income ratio lenders look at — that one compares monthly payments with monthly income, and our DTI calculator works it out.
Why one number isn't enough: track it monthly
Calculating your net worth once is useful. Tracking it every month is where the real value is. A single figure is a snapshot; twelve of them are a story. You see:
- The direction. Is it climbing? How fast? A $500 average monthly climb and a $2,500 one lead to very different futures.
- What moves it. A raise, an extra loan payment, a market dip, a new car.
- Debt shrinking. Watching the total owed fall each month is one of the best motivators there is.
- Milestones. Your first month above $0, the day you're debt-free except for the mortgage, your first $100k.
Markets go up and down, so some months will dip. That's fine. One lower month in a rising trend is noise; the long-run line is what counts.
A simple monthly net worth routine
- Pick a day — the 1st, or the day after payday.
- Update each balance from your bank, investment and loan apps.
- Refresh estimates (home, car) every three to six months, not every month.
- Write one line about what happened: "bonus to the brokerage", "paid off the Visa".
- Look at the change from last month and the trend over the year.
It takes about ten minutes the first time and two or three minutes after that. You can do it in a spreadsheet — or let an app keep the history for you.
Track your net worth with Summit
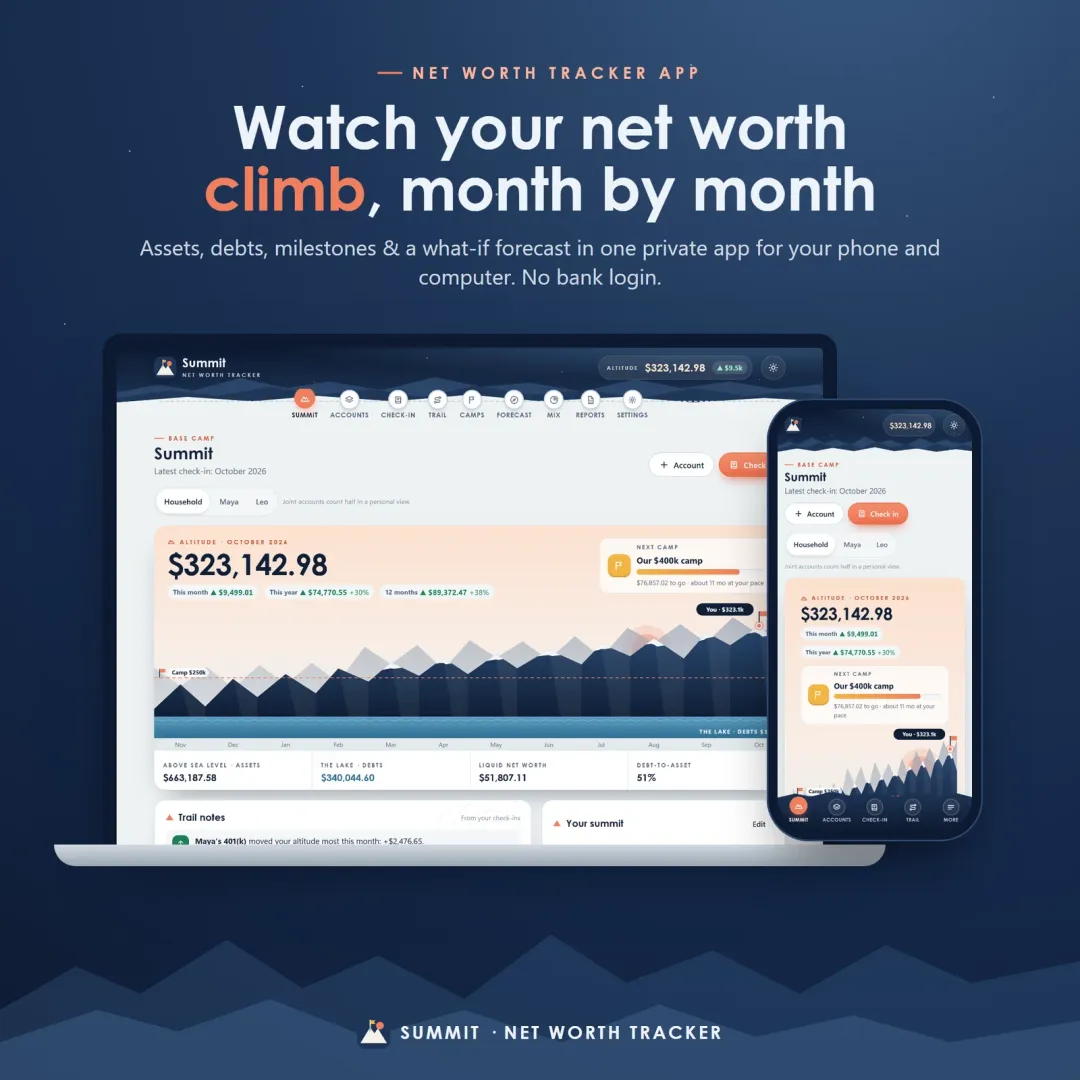
Summit is the VaultlyApps net worth tracker, built around exactly that monthly routine. It shows your net worth as a mountain: what you own rises above sea level, what you owe sits in a lake below, and each monthly check-in adds a new peak.
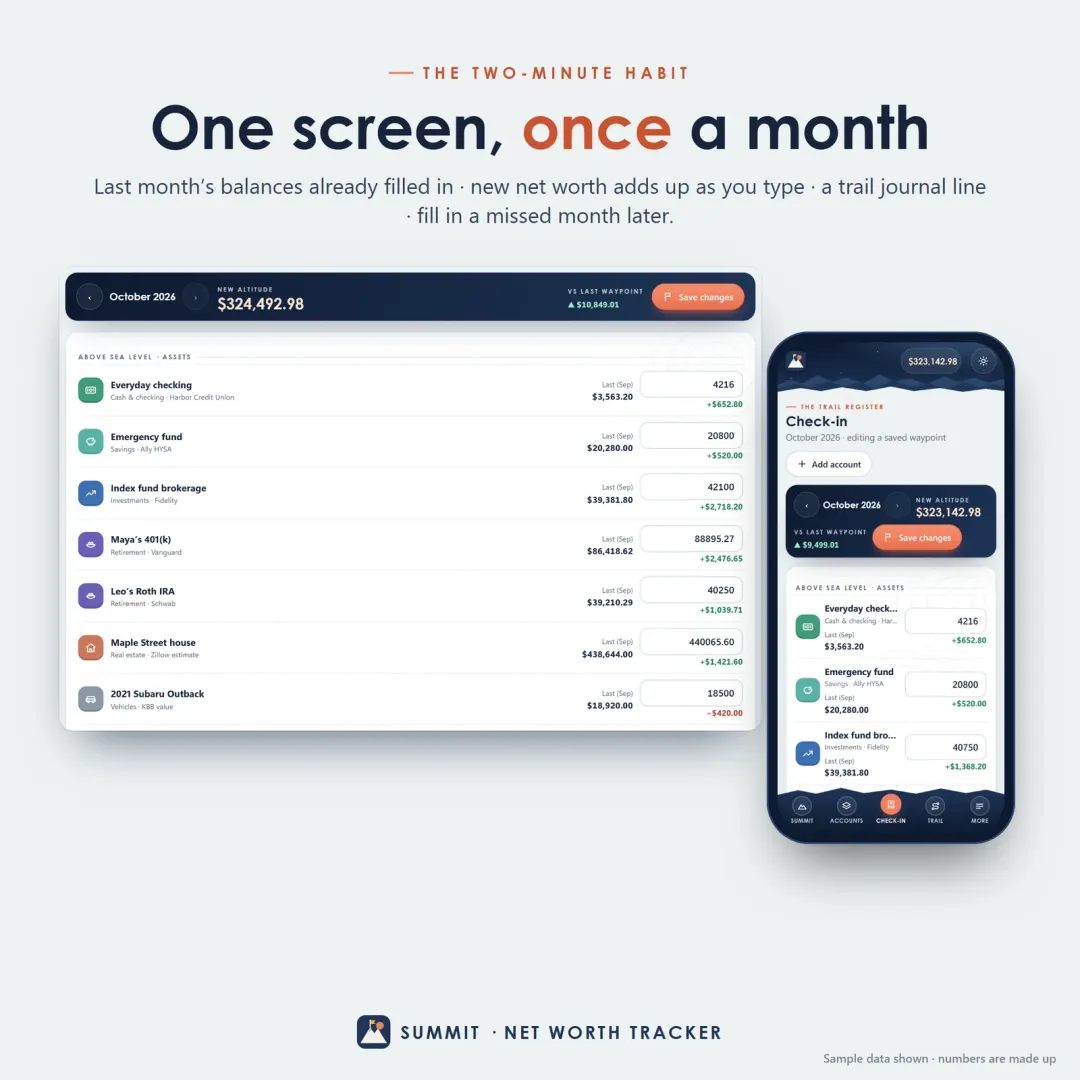
- Monthly check-in: every account on one screen with last month's balance already filled in; the new net worth adds up as you type.
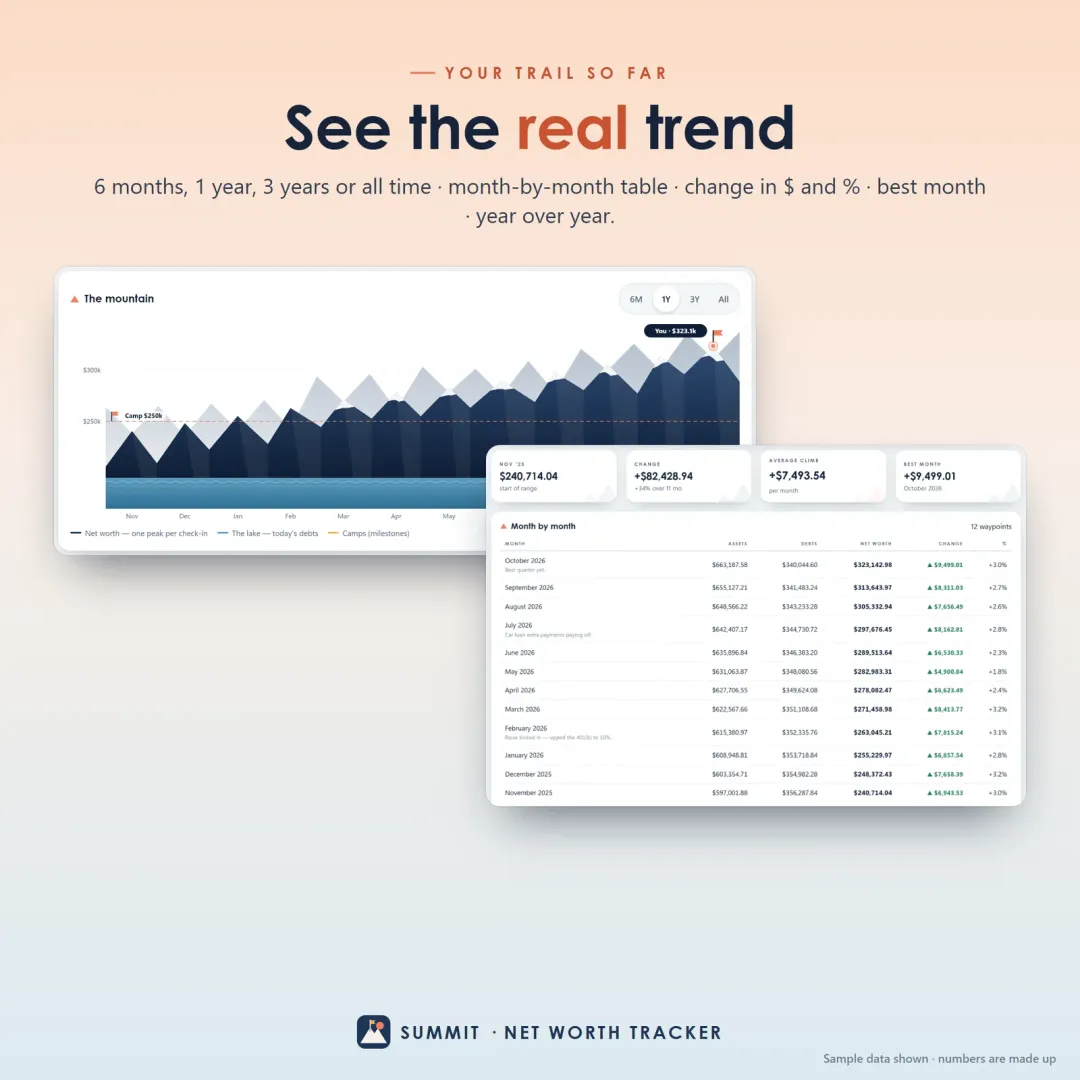
- History: a chart with one peak per month, a month-by-month table, your best month and year over year.
- Milestones ("camps"): above $0, debt-free, $10k up to $1M, plus your own — with the month you reached each one.
- Goal with an arrival date: how far up you are and when you'll get there at your current pace.
- Liquid net worth, debt-to-asset ratio, emergency runway and home equity, worked out for you.
- Couples: each account can be yours, your partner's or joint.
There's no bank login and no subscription; your numbers stay on your own devices. You can try the free demo with a sample household first.
How to grow your net worth
Every dollar of debt you pay off and every dollar you save raises your net worth by exactly that dollar. The biggest levers:
- Pay off high-interest debt first. Clearing a 24% credit card is like earning a guaranteed 24% return. The debt avalanche targets the highest rate first; Zero plans it month by month.
- Build an emergency fund. It stops surprises from becoming new debt — see how much emergency fund you need.
- Automate saving and investing on payday, before you can spend it.
- Invest for the long run and let compound growth work. The compound interest calculator shows what a steady monthly amount can grow into.
- Avoid new debt for things that lose value quickly, like a car that's more than you need.
- Spend on purpose. A budget that gives every dollar a job — such as Vault — frees up the money that grows your net worth.
Common net worth mistakes
- Using purchase prices for your home, car or valuables instead of what they'd sell for today.
- Counting monthly payments instead of the balance owed.
- Leaving out small debts like store cards or buy-now-pay-later plans.
- Changing methods month to month (for example, counting the 401(k) after tax one month and before tax the next).
- Checking daily. Market noise makes it stressful and tells you little. Monthly is enough.
- Comparing with averages. National net worth figures are skewed by very wealthy households. Compare with your own past months.
The bottom line
To calculate your net worth, list what you own at today's realistic value, list what you owe at today's balance, and subtract. Then look at two more numbers — liquid net worth and debt-to-asset ratio — to see how solid that total is.
The real power comes from doing it again next month, and the month after. Start with the free net worth calculator, and when you're ready to keep the history, milestones and forecast in one place, Summit makes the monthly check-in a two-minute habit.
This guide is general information, not financial or investment advice. Values and ratios are estimates based on the numbers you use.
Frequently asked questions
What is the formula for net worth?
Should I include my home and car?
Do retirement accounts count toward net worth?
Is a negative net worth bad?
How often should I calculate my net worth?
What is a good net worth for my age?
What's the fastest way to grow net worth?
Written by
Finance Specialist & Editor, VaultlyApps
Emma Whitfield writes and edits the VaultlyApps money guides and free calculators. Her focus is US household finance — budgeting on a real paycheck, paying down credit card and student debt, emergency funds and savings goals, renting — and the money side of freelancing and small-business income, from pricing and profit margins to self-employment tax. Every guide is researched against primary sources such as IRS publications and the CFPB, every number is checked in our tested calculators, and tax content is reviewed each year when new IRS figures come out. Emma is not a licensed financial adviser or tax preparer; her work is general education, not personal advice.
Researched against primary US sources, checked with our calculators and reviewed by a finance expert on our team. Written for US readers — general education, not financial, tax or legal advice. Editorial policy · Disclaimer