VaultlyApps logo VaultlyApps

Free calculator

Net Worth Calculator (Assets − Liabilities, With Liquid Net Worth)

Your net worth is everything you own minus everything you owe. List your assets and debts below to see your net worth, how much of it is liquid, your debt-to-asset ratio and what makes up the total.

By Updated Private — runs in your browser Free, no sign-up Save, print, PDF & CSV — with a QR code to reopen it

What you own (assets)

What you owe (debts)

Net worth = total assets − total debts. Liquid net worth = liquid assets − debts that aren’t a home loan.

Your net worth

Assets Debts

Liquid net worth


Debt-to-asset ratio


Home equity


Liquid share of assets


Biggest pieces

For readers in the United States. Estimates for planning only — not financial, investment, tax or legal advice. Disclaimer · How we check our numbers

Summit app icon

Want these numbers to update by themselves?

Summit — Net Worth Tracker — keeps this plan current as you log real payments. Try the free demo, no sign-up.

How to use the net worth calculator

  1. Under What you own, list each asset with today's value — cash, savings, investments, retirement, your home, your car. Tick liquid for money you could use within days.
  2. Under What you owe, list each debt with the balance you owe today — credit cards, student loans, auto loan, mortgage.
  3. Read your net worth, liquid net worth and debt-to-asset ratio on the right, and see which items make up the biggest part.

The net worth formula

Net worth = total assets − total liabilities

What you own (assets) Value What you owe (liabilities) Balance
Home (market value) $150,000 Mortgage $88,000
Savings & checking $12,000 Car loan $7,000
401(k) $18,000
Total assets $180,000 Total liabilities $95,000

Net worth: $180,000 − $95,000 = $85,000. Liquid net worth: the $12,000 of savings minus the $7,000 car loan = $5,000 (the mortgage is left out because it's tied to the home).

Liquid net worth vs net worth

Two people can have the same net worth and very different lives. One has most of it in home equity and a retirement account; the other has a cash cushion. Liquid net worth — liquid assets minus debts that aren't a mortgage — shows how much you could actually reach in an emergency. Pair it with an emergency fund target from our emergency fund calculator.

Debt-to-asset ratio

Debt-to-asset ratio = total liabilities ÷ total assets × 100

Ratio What it usually means
Under 30% Low. Most of what you own is yours.
30% – 60% Moderate. Common with a mortgage.
Over 60% High. Debts are a big share of your assets.

It's different from the debt-to-income ratio lenders use, which compares monthly debt payments with monthly income — work that out with the debt-to-income ratio calculator.

Net worth is a trend, not a number

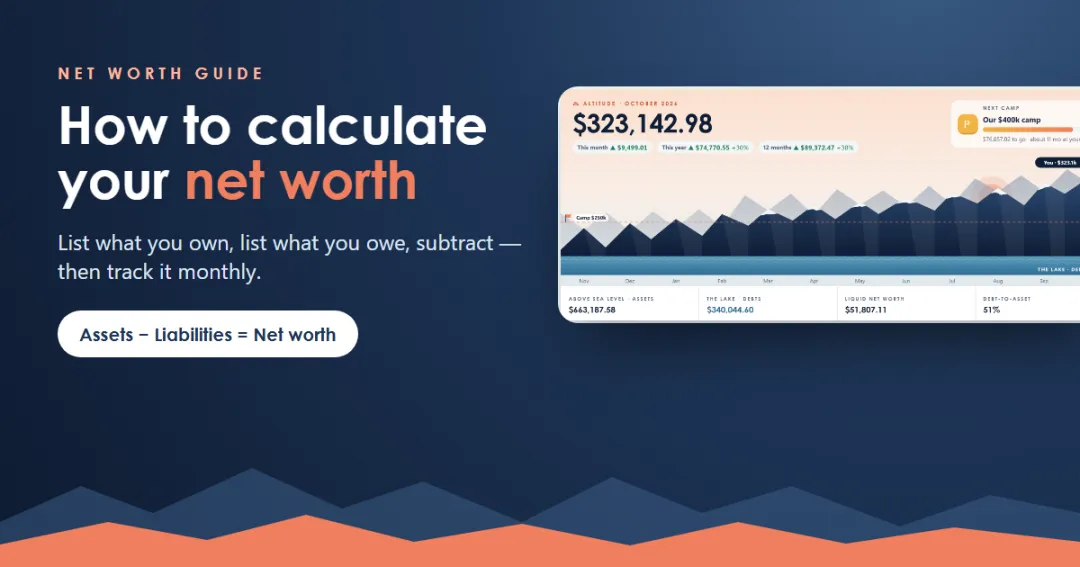
A single net worth figure is a snapshot. The real value is in tracking it month after month: you see debts shrinking, savings growing and the effect of every raise, windfall or market dip. Summit, our net worth tracker, makes that a two-minute monthly check-in — every account on one screen, a history chart with one peak per month, milestones from $0 to $1M and a forecast of where your net worth is heading. Read the full guide: how to calculate your net worth.

How to grow your net worth

  • Pay down high-interest debt first — every dollar off a 24% card is a guaranteed 24% return.
  • Automate saving and investing on payday so it happens before spending.
  • Keep an emergency fund so surprises don't go on a credit card.
  • Invest steadily for the long run; see what monthly investing can grow into with the compound interest calculator.
  • Value things honestly — use today's market value for your home and car, not the purchase price.
  • Check in monthly so you notice the trend early.

Save, print or share your result

Under the calculator you can save the calculation in your browser, copy a link that reopens it with your numbers, print a clean report or download it as a PDF (with a QR code that reopens the calculation), or download a CSV. Nothing is uploaded — saved calculations stay on your device.

Frequently asked questions

How do you calculate net worth?

Net worth = total assets − total liabilities. Add up everything you own (cash, savings, investments, retirement accounts, the market value of your home and car) and subtract everything you owe (credit cards, student loans, auto loans, mortgage and other debts). If you own $180,000 and owe $95,000, your net worth is $85,000.

What counts as an asset?

Anything with a cash value you could sell or use: checking and savings, emergency fund, brokerage and retirement accounts, crypto, the current market value of your home, vehicles and valuables, and the value of a business you own. Use what it would sell for today, not what you paid.

Should I include my house in my net worth?

Yes — include the home's estimated market value as an asset and the mortgage as a debt. The difference is your home equity. Many people also track liquid net worth, which leaves the home out, because you can't spend home equity easily.

What is liquid net worth?

Liquid net worth is the money you could use within days — cash, savings, brokerage accounts and similar — minus debts other than a mortgage. It shows how much flexibility you really have, which a big home-equity number can hide.

What is a good debt-to-asset ratio?

Debt-to-asset ratio = total debts ÷ total assets. Under about 30% is generally comfortable, 30% to 60% is common for homeowners with a mortgage, and above 60% means debts are a large share of what you own.

Can my net worth be negative?

Yes, and it's very common early on — especially with student loans or a new mortgage. A negative net worth just means you owe more than you own today. What matters most is the direction: tracking it monthly shows whether it's climbing.

How often should I calculate my net worth?

Once a month is ideal, for example on the 1st or on payday. It's often enough to see the trend and rare enough that daily market moves don't distract you.

Can I save, print or download my result?

Yes. Save it in your browser, copy a link that reopens it, print it, or download it as a PDF or CSV. The printout lists your assets and debts, your net worth, liquid net worth and debt-to-asset ratio, plus a QR code that reopens the calculation.

Written by

Emma Whitfield

Finance Specialist & Editor, VaultlyApps

Emma Whitfield writes and edits the VaultlyApps money guides and free calculators. Her focus is US household finance — budgeting on a real paycheck, paying down credit card and student debt, emergency funds and savings goals, renting — and the money side of freelancing and small-business income, from pricing and profit margins to self-employment tax. Every guide is researched against primary sources such as IRS publications and the CFPB, every number is checked in our tested calculators, and tax content is reviewed each year when new IRS figures come out. Emma is not a licensed financial adviser or tax preparer; her work is general education, not personal advice.

Researched against primary US sources, checked against independent calculators and reviewed by a finance expert on our team. Written for US readers — general education, not financial, tax or legal advice. Editorial policy · Disclaimer

From VaultlyApps

Apps that do this for you

Each one has a free live demo with sample data — open it in your browser, nothing to install.

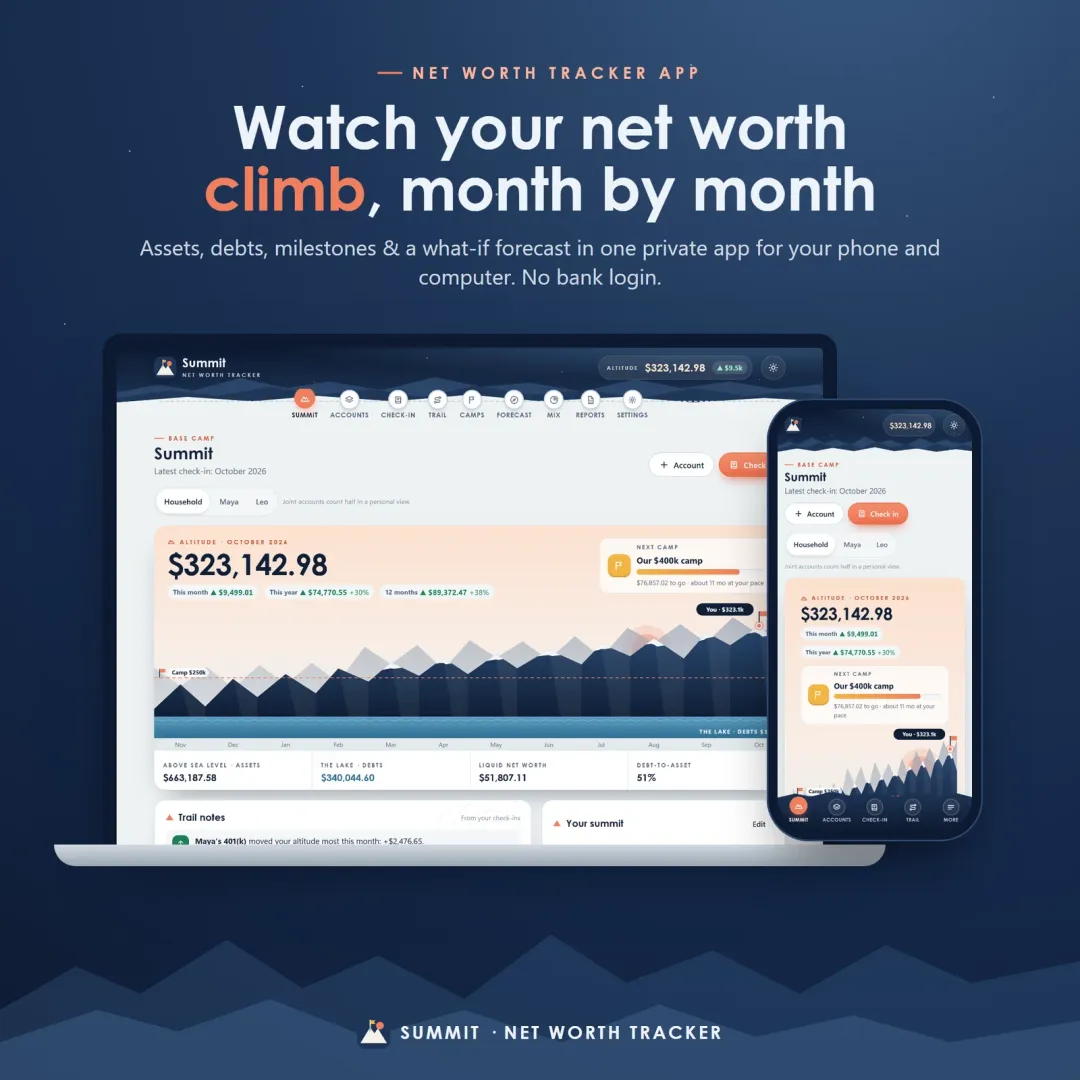
Summit net worth tracker app showing net worth as a mountain range with one peak per monthly check-in Live
Summit app icon

Summit

Net Worth Tracker

A private net worth tracker for your phone and computer — add what you own and what you owe, check in once a month and watch your net worth climb, with milestones, a what-if forecast and a printable Net Worth Statement.

Vault personal finance dashboard shown on a laptop and a phone, with the safe-to-spend number and cash-flow charts Live
Vault app icon

Vault

Personal Finance Dashboard

Your whole money picture on one private dashboard — safe-to-spend, budgets, bills, goals, debt payoff and net worth, on your phone and laptop.

Zero debt payoff planner with a road leading to a $0 finish flag and the projected debt-free date Live
Zero app icon

Zero

Debt Payoff Planner

See your debt-free date, compare the snowball and avalanche methods side by side, and watch extra payments pull the finish line closer.

Keep planning

Related calculators

All calculators

Further reading

Guides on this topic

All articles
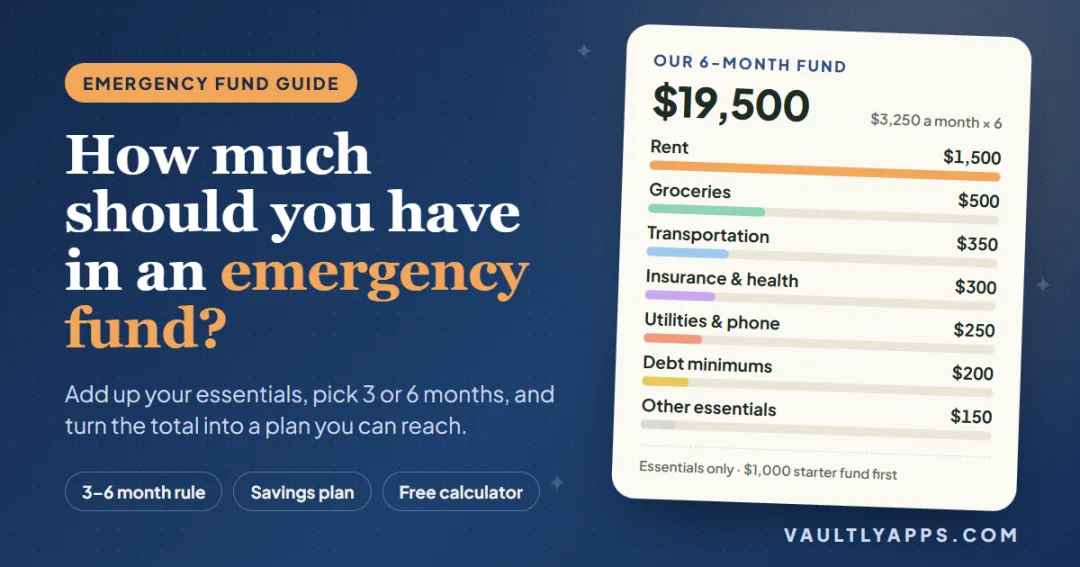
How much should you have in an emergency fund — a $19,500 six-month fund built from $3,250 of monthly essentials

Personal Finance

How Much Should You Have in an Emergency Fund?

How much emergency savings you really need, worked out step by step: add up your essentials, choose three, six or more months, and turn the total into a monthly plan you can actually reach.

7 min read

Try Summit free in your browser

A private net worth tracker for your phone and computer — add what you own and what you owe, check in once a month and watch your net worth climb, with milestones, a what-if forecast and a printable Net Worth Statement. The live demo uses sample data — nothing to install, no sign-up.

We use optional cookies for anonymous analytics. Nothing optional is set until you choose. Cookie policy