VaultlyApps logo VaultlyApps

Free calculator

DSCR Calculator: Debt Service Coverage Ratio for Rental Property Loans

Enter the rent, the price, your loan terms and the property's taxes, insurance and HOA. See your DSCR the way investment-property lenders work it out, the rent needed for their minimum, the biggest loan and purchase price you can get, and how the ratio changes with the interest rate.

By Updated Private — runs in your browser Free, no sign-up Save, print, PDF & CSV — with a QR code to reopen it

How your lender measures DSCR

Lease or market rent.

Parking, laundry, storage.

DSCR loans: usually 20–25%.

For NOI and cash flow.

Share of rent.

Your DSCR


PITIA a month


Rent needed


Max loan


Max price


0.601.001.201.60

Cash flow after vacancy and costs:

DSCR at other interest rates

Most DSCR loan lenders divide gross rent by PITIA (principal, interest, taxes, insurance and HOA). Commercial lenders use net operating income ÷ principal and interest. Lenders set their own minimums, rates and rent rules; this is an estimate.

For readers in the United States. Estimates for planning only — not financial, investment, tax or legal advice. Disclaimer · How we check our numbers

RentRoll app icon

Want these numbers to update by themselves?

RentRoll — Landlord Dashboard — keeps this plan current as you log real payments. Try the free demo, no sign-up.

How to use the DSCR calculator

  1. Pick the method. Most residential DSCR lenders use rent ÷ PITIA; commercial and portfolio lenders often use NOI ÷ debt service.
  2. Enter the monthly rent (lease or appraiser's market rent) and any other income.
  3. Enter the price, down payment, interest rate and term, plus yearly property tax, insurance and monthly HOA.
  4. Choose the lender's minimum DSCR, and set vacancy and repair costs for the NOI method and cash flow.

What DSCR lenders look for

DSCR What it means Typical lender response
Below 1.00 Rent doesn't cover the payment Declined, or a no-ratio loan at a higher rate
1.00–1.19 Rent just covers it Often approved, higher rate or more down
1.20–1.24 Some room to spare Approved by most lenders
1.25 and up Comfortable cushion Best pricing

Every lender sets its own grid, so get quotes from a few.

How the interest rate changes your DSCR

Same $300,000 rental, 25% down, $2,400 rent:

Rate PITIA DSCR
6.25% $1,810 1.33
6.75% $1,884 1.27
7.25% $1,960 1.22
7.75% $2,037 1.18
8.25% $2,115 1.13

A one-point rate change moves the ratio by about 0.1. Buying the rate down with points, a larger down payment, or an interest-only period can lift a deal over the line.

How to raise your DSCR

  • Put more down. A smaller loan lowers principal and interest.
  • Find a lower rate, or pay points to buy it down.
  • Raise the rent to market before refinancing; lenders use the lower of the lease and the appraiser's market rent.
  • Shop insurance and appeal the tax assessment. Both sit in PITIA; see how property taxes work.
  • Choose a property with lower HOA dues, which count in full.

DSCR vs cap rate vs cash-on-cash return

DSCR answers the lender's question: does the rent cover the loan? Cap rate measures the property's return without financing, and cash-on-cash return measures what your own cash earns. A good deal usually passes all three. Check them with the cap rate calculator, the cash-on-cash return calculator and the full rental property calculator. Refinancing after a rehab? DSCR loans are a common exit for the BRRRR method.

Remember the real costs

A DSCR of 1.25 doesn't mean 25% profit. Lenders' rent ÷ PITIA ignores vacancy, repairs, capital expenses and management, which can take 20–35% of rent. That's why the calculator also shows cash flow after vacancy and costs. New to rentals? Start with how to become a landlord.

Run your rentals like a business

RentRoll is a landlord dashboard that tracks rent, expenses, leases and cash flow for every property, so your numbers are ready when a lender asks. Try the free demo with sample properties.

An estimate; lenders' rules and rates vary. Not financial advice.

Frequently asked questions

How do you calculate DSCR for a rental property?

Most DSCR loan lenders divide the monthly rent by PITIA: principal, interest, property taxes, insurance and HOA dues. $2,400 of rent against a $1,960 PITIA payment is a DSCR of 1.22.

What is a good DSCR?

1.25 or higher qualifies with most lenders at their best rates. Many accept 1.0 to 1.2 with a higher rate or a bigger down payment, and some offer no-ratio loans below 1.0 at a premium.

What does a DSCR of 1.0 mean?

The rent exactly covers the mortgage payment, taxes, insurance and HOA. Below 1.0 the property doesn't pay for itself and you cover the gap from your own pocket.

Do DSCR loans check my income?

No. DSCR loans qualify the property on its rent instead of your tax returns or W-2s, which is why self-employed investors and people with several rentals use them. Lenders still check credit (often 620–680+), reserves and the appraisal.

How much down payment does a DSCR loan need?

Usually 20–25% for a purchase, sometimes 30% for a low ratio, short-term rental or a lower credit score. Rates are typically 0.5–2 percentage points above a regular mortgage.

Is DSCR the same as NOI ÷ debt service?

That's the commercial version: net operating income (rent minus vacancy, repairs, management, taxes and insurance) divided by principal and interest. It gives a lower ratio for the same property. Switch the method in the calculator to see both.

Written by

Emma Whitfield

Finance Specialist & Editor, VaultlyApps

Emma Whitfield writes and edits the VaultlyApps money guides and free calculators. Her focus is US household finance — budgeting on a real paycheck, paying down credit card and student debt, emergency funds and savings goals, renting — and the money side of freelancing and small-business income, from pricing and profit margins to self-employment tax. Every guide is researched against primary sources such as IRS publications and the CFPB, every number is checked in our tested calculators, and tax content is reviewed each year when new IRS figures come out. Emma is not a licensed financial adviser or tax preparer; her work is general education, not personal advice.

Researched against primary US sources, checked against independent calculators and reviewed by a finance expert on our team. Written for US readers — general education, not financial, tax or legal advice. Editorial policy · Disclaimer
From VaultlyApps

Apps that do this for you

Each one has a free live demo with sample data — open it in your browser, nothing to install.

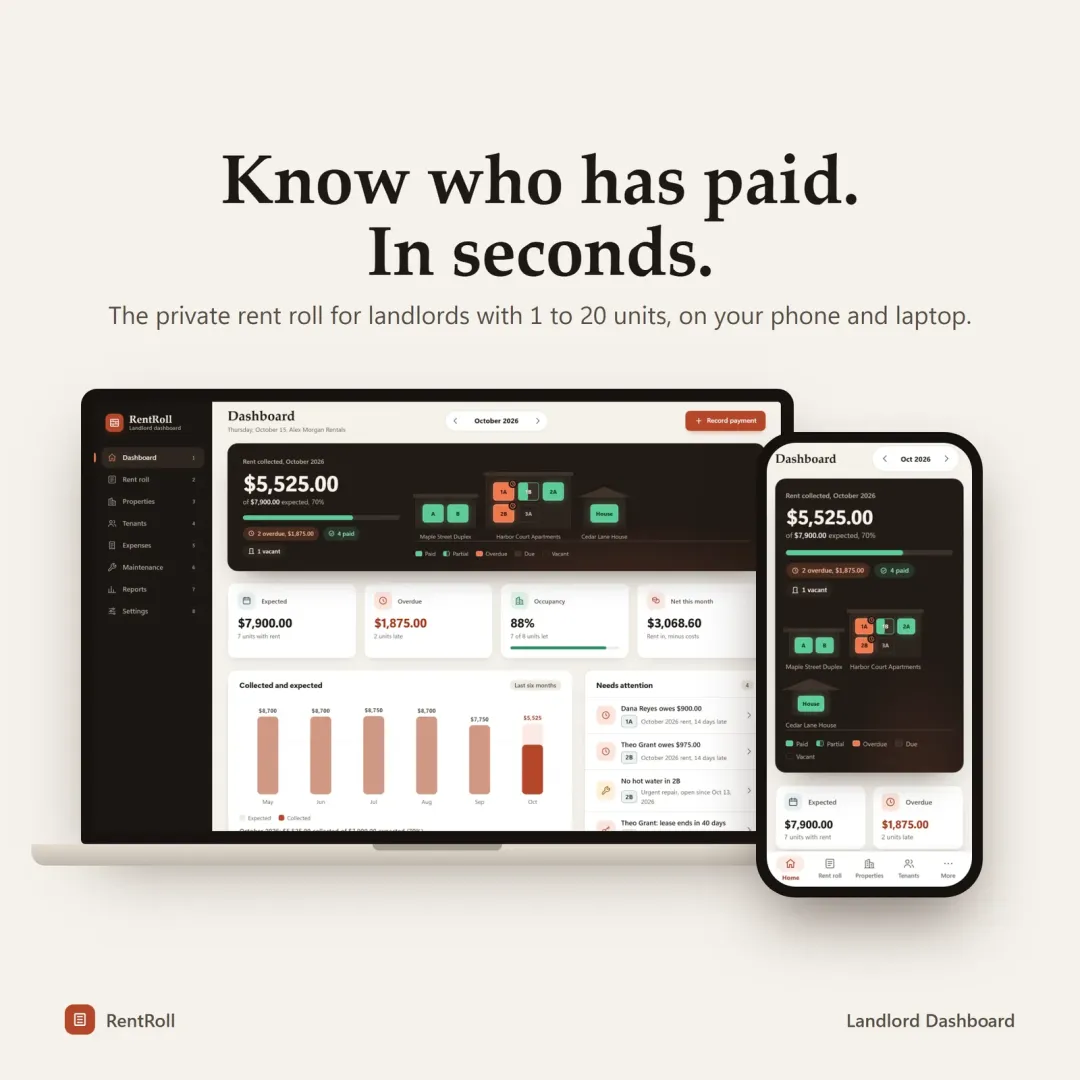
RentRoll landlord dashboard with buildings whose windows light up when rent is paid Live
RentRoll app icon

RentRoll

Landlord Dashboard

A private rent roll and property manager for landlords with 1 to 20 units — rent collection, late fees, leases, maintenance and Schedule E tax reports.

Keep planning

Related calculators

All calculators

Cap Rate Calculator

NOI, cap rate and the property's value at any market cap rate.

Open calculator

Further reading

Guides on this topic

All articles
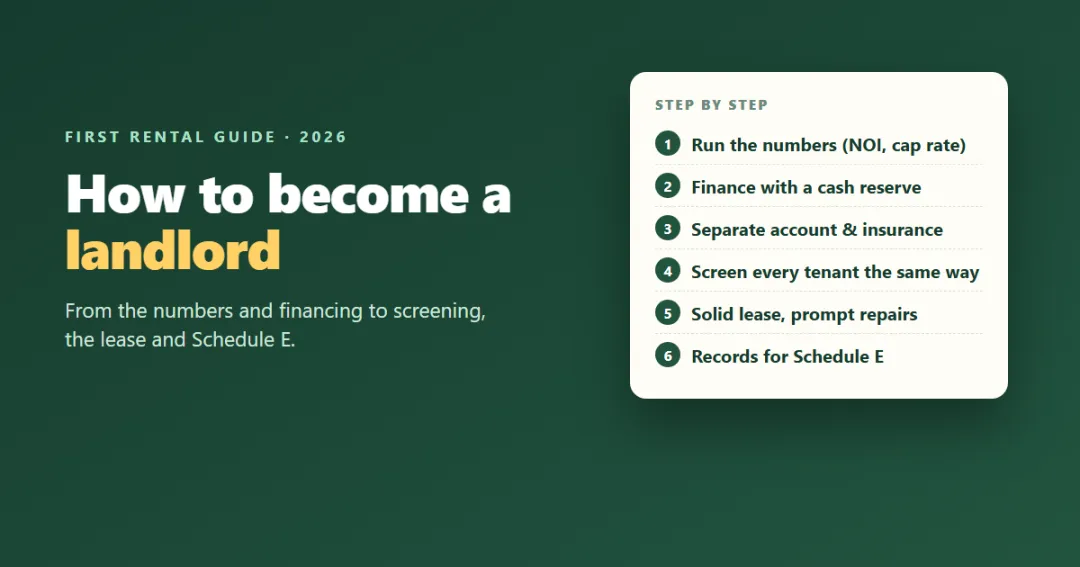
How to become a landlord — a house with keys and a checklist from numbers to first tenant

Personal Finance

How to Become a Landlord: A Step-by-Step Guide for Your First Rental (2026)

Becoming a landlord starts long before the first tenant: running the numbers, financing, setting up the business side, screening, leases and keeping records for taxes. Here's a step-by-step guide for your first rental property, with the key formulas, a worked example and the mistakes new landlords make most.

7 min read
How property taxes work — assessed value minus exemptions times the mill rate equals your yearly tax

Personal Finance

How Property Taxes Work: Assessments, Mill Rates, Exemptions and How to Lower Your Bill

Your property tax bill comes from three numbers: your home's assessed value, any exemptions and your local tax rate. Here's how each one works, why the same house can cost $1,000 or $7,800 a year depending on the state, how escrow and reassessment change your payment, and five legal ways to pay less.

7 min read
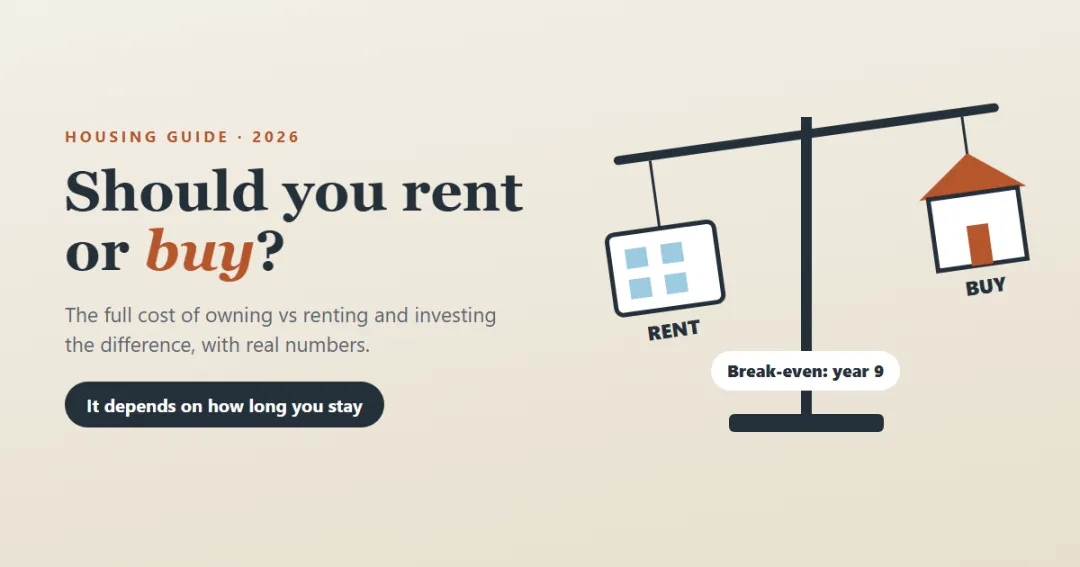
Rent or buy — a scale weighing a rented apartment against a house with a mortgage

Personal Finance

Should You Rent or Buy a House in 2026? How to Decide With Real Numbers

Buying isn't automatically smarter than renting, and rent isn't money thrown away. Here's how to compare the full cost of owning with renting and investing the difference, what the break-even point is, how rates, home prices and how long you stay change the answer, and a checklist to decide.

7 min read

Try RentRoll free in your browser

A private rent roll and property manager for landlords with 1 to 20 units — rent collection, late fees, leases, maintenance and Schedule E tax reports. The live demo uses sample data — nothing to install, no sign-up.

We use optional cookies for anonymous analytics. Nothing optional is set until you choose. Cookie policy